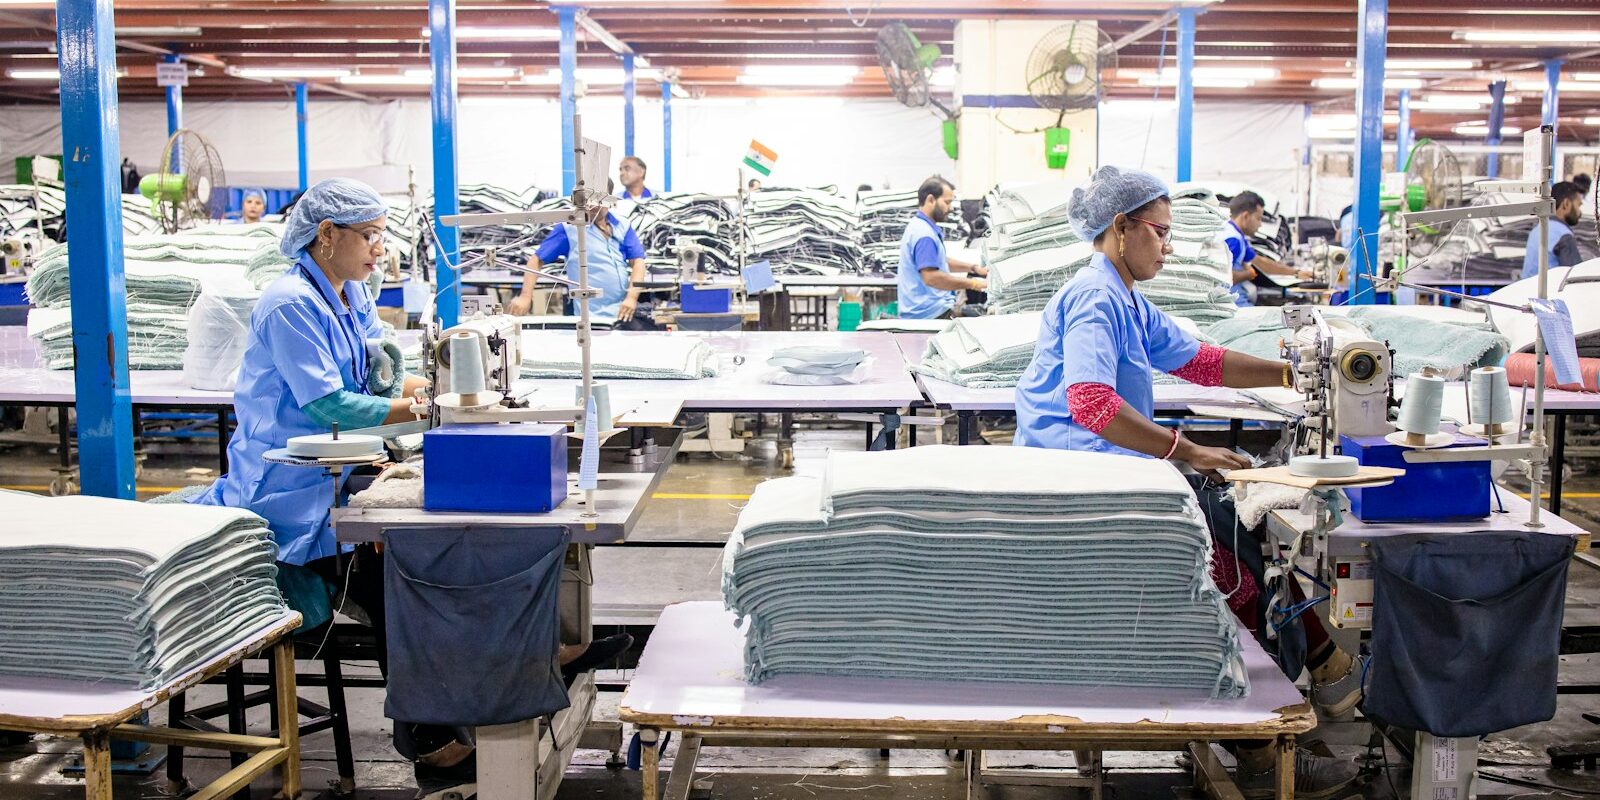
Kenya is one of Africa’s leading apparel exporters, and a new textile or garment manufacturer entering the market must navigate a regulatory stack beyond standard company registration. A manufacturer needs to decide whether to operate inside an Export Processing Zone (EPZ) or a Special Economic Zone (SEZ), understand how continued US market access under the African Growth and Opportunity Act (AGOA) affects export strategy, comply with labour and workplace safety law, meet Kenya Bureau of Standards (KEBS) product requirements, and obtain environmental licensing before construction begins. This guide sets out that framework in the order an investor will typically work through it.
Choosing Between an EPZ and an SEZ
Kenya operates two parallel zone regimes for export oriented manufacturing. The older is the Export Processing Zones Act (Chapter 517), administered by the Export Processing Zones Authority (EPZA). An EPZ enterprise must be incorporated in Kenya to produce goods or services for export from within a designated zone, and goods generally may not leave the zone except for export. EPZA’s own published programme terms give a licensed enterprise a ten year corporate tax holiday followed by a reduced rate, a ten year withholding tax holiday, a 100% investment deduction on new capital expenditure, and perpetual exemption from VAT and import duty on machinery, raw materials and inputs. EPZA also runs an SME Development Programme aimed at textile and apparel, leather and horticulture businesses with under KES 40 million in initial capital, fewer than 100 employees and at least 75% Kenyan ownership, offering built warehousing at reduced rents with a rent free setup period.
The newer regime is the Special Economic Zones Act, No. 16 of 2015 (Chapter 517A), administered by the Special Economic Zones Authority (SEZA). SEZs permit a broader mix of manufacturing, logistics and service activities and do not require the strict export orientation an EPZ does. Per SEZA’s published fiscal incentives, a licensed SEZ enterprise pays corporate tax at 10% for the first ten years, 15% for the next ten years and the standard rate thereafter; imports into the zone are fully exempt from VAT, excise duty and import duty, with local supplies zero rated; withholding tax on dividends and property transfer gains to non-residents is exempt, and on royalties, interest and service fees exempt for the first ten years; and enterprises get a 100% capital allowance on qualifying buildings and machinery, plus a single SEZA licence replacing multiple county and sectoral permits. A manufacturer selling into the East African regional market as well as exporting will generally find the SEZ regime the better fit.
Both regimes sit within a wider policy push. The State Department for Industry’s Strategic Plan 2023 to 2027 names textile and apparel a priority value chain under Kenya’s Bottom-up Economic Transformation Agenda, alongside leather, dairy and pharmaceuticals. A draft National Cotton, Textile and Apparel Policy circulated by the same ministry in 2024 proposes to expand cotton production and deepen local fabric manufacturing, but it remains a draft, not yet binding law.
AGOA and Access to the US Market
For a Kenyan apparel manufacturer, continued eligibility under AGOA, the US programme granting qualifying sub-Saharan African countries duty free access for a wide range of products, is the single most consequential trade question. Kenya has for some years been the largest apparel exporter to the US under AGOA, and the sector accounts for a large majority of Kenya’s exports to that market, supporting tens of thousands of factory jobs concentrated in its export processing zones. A US federal government notice published in mid-2026 confirmed Kenya as one of 33 countries designated as AGOA beneficiaries for that eligibility cycle. Eligibility is reviewed annually against statutory criteria covering market based economic reform, rule of law, removal of barriers to US trade and investment, and protection of internationally recognised worker rights, and can be reviewed out of cycle if a specific compliance concern is raised.
The programme’s own authorisation has been a live issue. AGOA’s prior statutory authorisation lapsed at the end of September 2025, was temporarily restored in early 2026, and Congress subsequently passed legislation in September 2026 extending it through 31 December 2028. Kenya’s Cabinet Secretary for Trade and Investment publicly welcomed the extension as removing uncertainty over manufacturers’ machinery investment, workforce and supply contract decisions. Because AGOA renewal has repeatedly come down to short extensions, a manufacturer building an export plan around it should treat the authorisation as time limited, monitor the annual eligibility review, and price that renewal risk into long term contracts and financing.
A related feature is the third country fabric provision, letting an eligible lesser developed beneficiary country such as Kenya source fabric from outside the AGOA region, cut and assemble it domestically, and still export the finished garment to the US duty free. This has been central to Kenya’s apparel export model, since most fabric used locally is imported rather than woven in Kenya, a gap the draft Cotton, Textile and Apparel Policy flags as a priority for domestic investment.
Labour and Workplace Safety Compliance
A garment or textile factory is labour intensive and sits squarely within the Employment Act, No. 11 of 2007, and the Occupational Safety and Health Act, No. 15 of 2007 (OSHA). Under the Employment Act, a contract of service lasting three months or more must be in writing, setting out job description, place of work, hours, remuneration and other prescribed particulars in a language the employee understands. Employers must provide at least one rest day in seven, and employees are entitled to not less than 21 working days of paid annual leave after twelve months of service, not less than seven days of paid sick leave after two months, three months of paid maternity leave and two weeks of paid paternity leave. Termination of a monthly paid contract requires 28 days’ written notice, and sections 41, 43 and 45 require the employer to notify the employee of the reasons for a proposed termination, hear any representations, and prove the reason for termination, failing which it is deemed unfair. The Act also prohibits forced labour and prohibits employing a child under 13, permitting only light work for those aged 13 to 16.
OSHA adds factory specific obligations. Section 6 sets out the occupier’s general duty to ensure health and safety, and section 7 requires a written safety and health policy statement. Every factory must be registered as a workplace under sections 43 to 45, and larger workplaces must establish a safety and health committee under section 9. Employers must notify accidents and dangerous occurrences under section 21 and occupational diseases under section 22. Enforcement sits with the Director and with occupational safety and health officers appointed under section 26, with the National Council for Occupational Safety and Health, established under section 27, providing national oversight. Given the mechanical equipment, dust, dyes and dense production floors typical of textile factories, workplace registration, a written safety policy and a functioning safety committee should be treated as day one requirements, not afterthoughts.
KEBS Standards and Product Certification
Textile and apparel products manufactured or imported for sale in Kenya fall under the Kenya Bureau of Standards’ quality control regime. Locally manufactured products covered by a declared Kenya Standard require a Standardisation Mark (S-Mark) permit, issued after KEBS reviews the manufacturer’s quality control procedures, inspects the factory and tests product samples; an S-Mark permit runs for two years and the permit number must appear on labelling. A voluntary Diamond Mark (D-Mark) scheme recognises a higher standard of quality management, runs for four years, and carries automatic S-Mark qualification. Applications are managed through KEBS’s Kenya Inspection Management System (KIMS) portal, with fees scaled by enterprise size. On the import side, KEBS inspects goods, entry documentation and packing lists at the port of entry and samples them for testing; any consignment, including imported fabric, trims or finished garments, that fails the relevant Kenya Standard can be rejected and returned to the supplier at the supplier’s cost, so contracts with foreign input suppliers should require compliance with the applicable Kenya Standard before shipment.
NEMA Environmental Licensing
Before a textile or apparel facility can be constructed and commissioned, the project proponent must engage the National Environment Management Authority (NEMA) under the Environmental Management and Coordination Act, No. 8 of 1999 (EMCA). EMCA prohibits any licensing authority from issuing an operating licence for a project requiring environmental assessment until NEMA has issued an EIA licence. Depending on scale and whether the process involves dyeing, wet processing, boiler operation or effluent discharge, a project may proceed by a shorter Project Report or may require a full Environmental Impact Assessment Study, moving through scoping and an approved terms of reference, baseline investigation, a study report, review by NEMA and relevant lead agencies, and a decision to approve, approve with conditions, or reject, with a right of appeal. NEMA charges an assessment fee calculated as a percentage of estimated project cost, subject to a prescribed minimum; a manufacturer should confirm the current rate with NEMA at application time, since the fee has been revised more than once in recent years. An approved facility remains subject to periodic environmental audits, and wastewater treatment for dyeing operations and disposal of textile waste should be built into facility design from the outset rather than retrofitted after an audit finding.
How We Can Help
Clay & Associates Advocates advises textile, apparel and other manufacturing investors on structuring Kenyan operations, choosing between EPZ and SEZ licensing, negotiating zone development and lease agreements, and building compliant labour, safety and environmental programmes from the ground up, as well as on AGOA and export compliance issues affecting supply and offtake contracts. Contact our Regulatory Compliance team or our Corporate & Commercial team to discuss setting up a textile or apparel manufacturing operation in Kenya.
Sources: Export Processing Zones Act (Chapter 517), sections 23 and 25, Kenya Law; Export Processing Zones Authority, EPZ Program; Special Economic Zones Act, No. 16 of 2015 (Chapter 517A), sections 10, 35 and 38, Kenya Law; Special Economic Zones Authority, Fiscal Incentives; Special Economic Zones Authority, Administrative Incentives; Employment Act, No. 11 of 2007, sections 4, 9, 10, 27 to 30, 35, 41, 43, 45 and 56; Occupational Safety and Health Act, No. 15 of 2007, sections 6, 7, 9, 21, 22, 23, 26, 27 and 43 to 45, Kenya Law; Kenya Bureau of Standards, Marks of Quality; Kenya Bureau of Standards, Import Inspection; Environmental Management and Coordination Act, No. 8 of 1999; National Environment Management Authority, Environmental Impact Assessment; US Federal Register, Notice of 2026 AGOA Beneficiary Sub-Saharan African Countries; Office of the United States Trade Representative, List of AGOA Eligible and Ineligible Countries; State Department for Industry, Strategic Plan 2023 to 2027; Ministry of Investments, Trade and Industry, Draft National Cotton, Textile and Apparel Policy, 2024.
Frequently asked questions
Should a new textile manufacturer set up in an EPZ or an SEZ?
It depends on the sales mix. An EPZ enterprise must produce almost entirely for export and gets a ten year corporate tax holiday and duty free inputs, suiting a manufacturer supplying US or European buyers. An SEZ enterprise faces a lower but non-zero tax rate from year one and has more flexibility to sell into the Kenyan and regional market, suiting a mixed export and domestic customer base.
Is Kenya currently eligible for AGOA, and how long will that last?
Yes, Kenya remains a designated AGOA beneficiary, and the programme’s authorisation was recently extended by the US Congress through 31 December 2028 after a lapse and temporary restoration in 2025 and 2026. Eligibility is reviewed annually against US statutory criteria, so a manufacturer should not treat continued access as guaranteed for the full period.
Does a textile factory need a full Environmental Impact Assessment before it can be built?
Most textile and apparel facilities need at least an EIA Project Report to NEMA, and a full EIA Study is usually required where the process involves dyeing, wet processing or effluent discharge. No licensing authority may issue an operating licence until NEMA has issued the EIA licence.
What KEBS certification does a Kenyan garment manufacturer need before selling locally made products?
A manufacturer producing goods covered by a declared Kenya Standard generally needs a Standardisation Mark permit, obtained after a factory inspection and product testing, valid for two years. Manufacturers exceeding the applicable standard can apply for the voluntary Diamond Mark instead, which carries automatic S-Mark qualification.